Home insurance in Tenerife: the complete guide for expats
In short: a Spanish home policy has two parts, buildings (continente) and contents (contenido). Insure the buildings for the cost of rebuilding, not the market price, and the contents for what it would cost to replace them. If the amounts are too low, the insurer can pay only part of a claim. Extraordinary events such as floods or volcanic eruptions are covered through the Consorcio de Compensación de Seguros.
Buying or renting a home in Tenerife is exciting. Insuring it can be confusing: the policy is in Spanish, the terms are different from those at home and the details matter. This guide explains how home insurance works in Spain and how to choose the right cover.
Buildings and contents: what is what
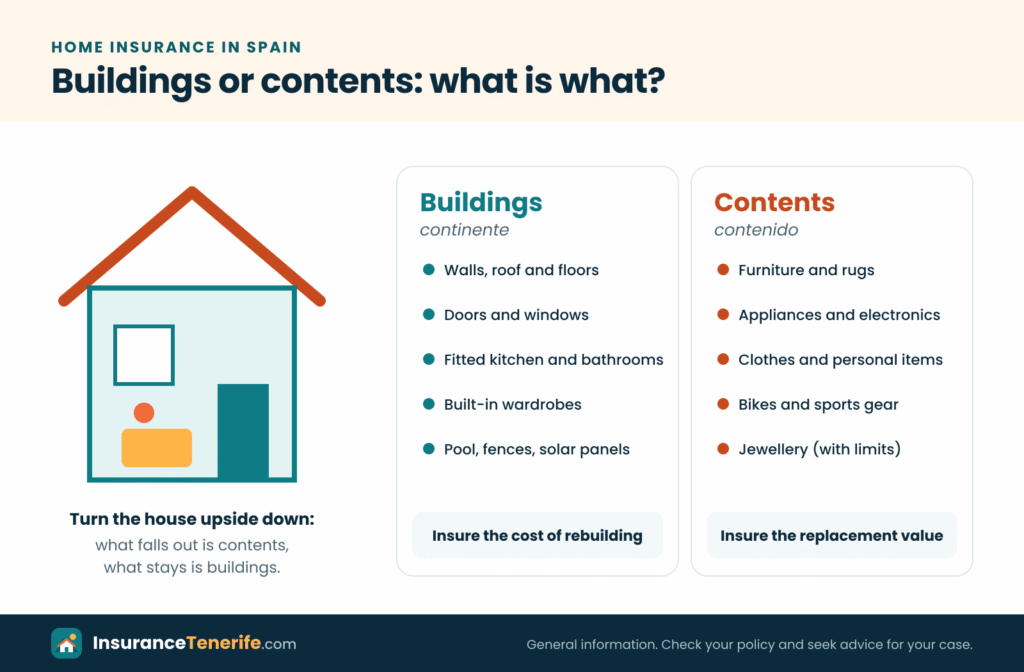
Buildings (continente) covers the structure and everything fixed to it: walls, floors, roof, doors and windows, fitted kitchen, bathrooms, built-in wardrobes, pool and fences. Contents (contenido) covers what you could take with you if you moved: furniture, electrical appliances, clothes, electronics and personal belongings.
If you own an apartment, the community of owners insures the common areas and the main structure of the building. You still need to insure your own apartment and its contents. If you rent, the landlord usually insures the building, and you only need tenant insurance for your belongings and liability.
How much should I insure?
This is where most mistakes happen. The buildings sum should be the cost of rebuilding the property, not what you paid for it. The market price includes the land and the location, which do not burn down. The contents sum should be what it would cost to replace your belongings today.
If you insure for less than the real value, Spanish law (article 30 of the Insurance Contract Law) allows the insurer to apply the under-insurance rule (regla proporcional) and pay only part of the claim.
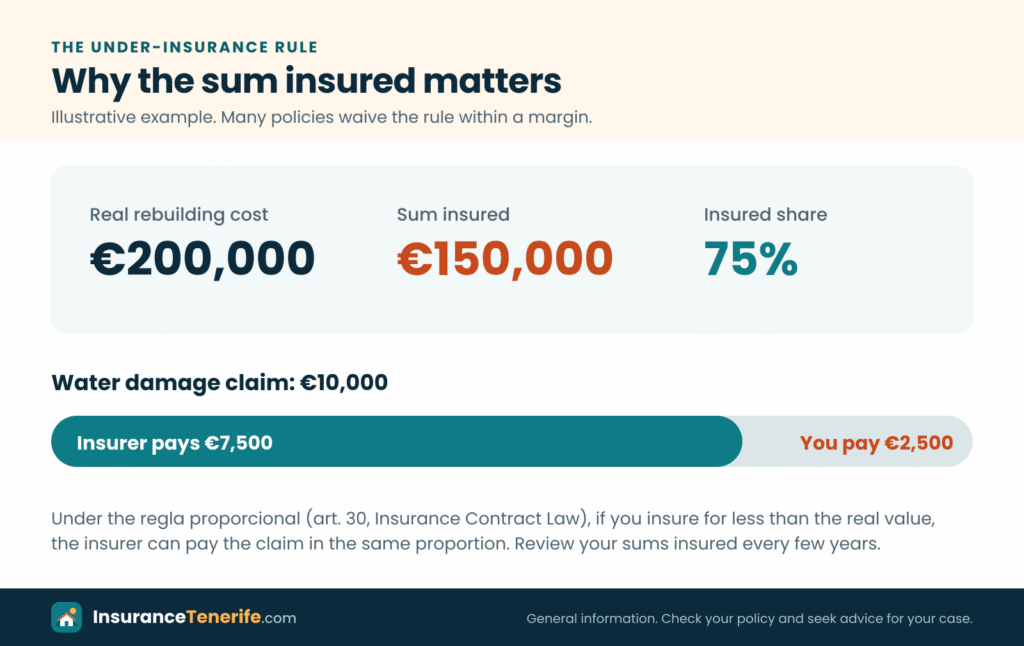
Some policies include a “first loss” option or waive the rule within a margin. We check this for you when comparing offers.
The most common claims
- Water damage: leaks and burst pipes, including finding and repairing the leak. Check whether the policy covers the search for hidden leaks.
- Liability towards neighbours: water from your flat damaging the one below.
- Glass and sanitary ware: broken windows, glass ceramic hobs or shower screens.
- Electrical damage: appliances damaged by power surges.
- Theft: with conditions on locks, empty periods and valuables.
Volcanoes, floods and storms: the Consorcio
Every home policy in Spain includes cover for extraordinary risks through the Consorcio de Compensación de Seguros, a public body that pays claims for events such as floods, volcanic eruptions, earthquakes and exceptional winds. A small surcharge for it appears on your receipt. The Consorcio applies its own rules, for example on the wind speeds considered exceptional, so ordinary storm damage is handled by your insurer within the policy limits.
Holiday homes and empty periods
If you spend part of the year away, tell your insurer. Some policies limit theft cover after a number of consecutive days without anyone living in the home, and require all locks and shutters to be closed. If you rent the property to tourists, you need a policy that accepts holiday-let use and includes liability towards guests; a standard home policy is usually not enough.
Mortgage? You can choose your insurer
Banks require buildings cover for mortgaged properties, but they cannot force you to take their own policy. You can present an equivalent policy from another insurer, and many people save money every year by doing so. We prepare the documents the bank needs.
Checklist before you buy a policy
- Sums insured: rebuilding cost and replacement value of contents.
- Excess (franquicia): how much you pay per claim.
- Hidden leaks, electrical damage and glass included?
- Conditions for empty periods and valuables.
- Liability limit: at least several hundred thousand euros is common.
- Optional extras: anti-squatter legal cover, home assistance and legal protection.
Ready to compare? Visit our home insurance in Tenerife page or ask us for a free quote in English.
Need advice for your own case?
Our team will explain your options in English and compare several insurers for you, free of charge.
Get a free quote